Every time I show a home to a veteran in World Golf Village, the same question comes up in the driveway: can you use a VA loan in World Golf Village, and with rates over 7%, is it even worth it?
I get it. I served in the Florida Army National Guard, and I remember how confusing the benefit felt the first time I looked at it. I also live here in 32092, so this one is close to home.
Here is the short version: Yes, you can use a VA loan in World Golf Village and everywhere else in 32092, St. Augustine, as long as the home meets VA property standards and appraises for the price.
In the last 12 months, 262 homes in 32092 sold to buyers using a VA loan, about 1 in 7 sales. With rates around 7%, the single most useful thing a VA buyer can do right now is ask the seller to help with the payment. VA lets a seller pay your normal closing costs with no cap, plus up to 4% of the home’s value in extra concessions, and that 4% can fund a temporary rate buydown. Most buyers never ask.
Veterans Day is Wednesday, November 11. If you’ve earned this benefit, here’s how to get the most out of it in our corner of St. Johns County.
Prefer to watch? I walk through all of this in about 5 minutes on my YouTube channel, St. Johns Living & Listings.
Can you use a VA loan in World Golf Village?
Yes. A VA loan is a mortgage from a regular lender, with the Department of Veterans Affairs guaranteeing part of it. There’s no list of “VA neighborhoods.” If the home meets VA’s basic property standards and appraises for the price, the benefit works in King & Bear, Murabella, Markland, Samara Lakes, SilverLeaf, Trailmark, Grand Oaks, Bannon Lakes, Shearwater or anywhere else in 32092. My neighborhood guides cover the bigger picture of World Golf Village and the rest of St. Johns County.
Here is what the benefit actually gives you, straight from the VA’s own pages:
- No down payment required in most cases.
- No monthly mortgage insurance. A conventional buyer putting 5% down usually pays it. You don’t.
- No VA loan limit if you have full entitlement. Per the VA’s entitlement page, your lender still has to approve the amount based on your income, credit and debts, and the home still has to appraise.
- A one-time funding fee, unless you’re exempt. More on that below.
A 32092 neighborhood I know from the inside: Samara Lakes
Samara Lakes was my first home. I bought it new in 2005, after I came off active duty, and lived there until 2017. I served as HOA president for a time, helped organize and start Food Truck Friday, and got the St. Johns County library bookmobile to add Samara Lakes as a stop. So when I say VA buyers are part of the fabric out here, I mean it.
The numbers back that up. Over the past 12 months, 8 of the 38 homes that sold in Samara Lakes went to VA buyers. That’s about 1 in 5, higher than the 32092 average. (Northeast Florida MLS via flexmls, Samara Lakes residential closed sales, October 2025 to September 2026, pulled October 28, 2026.)
VA loans are already common in 32092
I pulled every closed residential sale in 32092 from our MLS for the 12 months from October 2025 through September 2026.
| 32092 closed sales, Oct 2025 to Sept 2026 | Number | What it means |
|---|---|---|
| All closed residential sales | 1,877 | The whole 32092 market for the year |
| Bought with a VA loan | 262 (14%) | About 1 in 7 buyers. Sellers here see VA offers all the time |
| Conventional loan | 943 (50%) | Still the most common loan type |
| Cash | 384 (20%) | One in five buyers paid cash |
| VA sales with seller concessions | 112 of 262 (43%) | Asking the seller for help is normal, not pushy |
| Typical concession on those sales | $13,369 (median), about 2.9% of price | Real money toward closing costs, fees or a buydown |
| Median VA sale price | $490,000 | VA buyers are shopping the heart of the 32092 market |
| VA sale price vs. final list price | 99.5% (median) | Concessions didn’t mean lowball prices |
The VA buyers came from all over 32092. Trailmark, SilverLeaf, Silver Falls, Shearwater, Brook Forest and Silver Meadows had the most VA sales. And notice the concessions line: almost half of VA buyers here got the seller to chip in, and they still paid close to full price. That tells me most sellers would rather help with costs than cut the price.
What do VA loan rates look like right now?
Rates went up fast this fall. The average 30-year fixed VA rate was about 7.07% on October 7, 2026, up from roughly 6.05% in July and 6.45% in early September, after the Federal Reserve’s September rate hike. For comparison, Freddie Mac’s weekly survey put the conventional 30-year average at 7.32% on October 22, 2026.
VA rates usually run a bit below conventional rates because of the government guarantee. But “a bit lower” is still around 7%, and that’s real money.
The math on a $450,000 home
Here’s a simple example, principal and interest only:
- Price: $450,000, nothing down
- First-use funding fee of 2.15%: $9,675, rolled into the loan
- Loan amount: $459,675
- At 7.00%: about $3,058 a month
Now add the Florida part. Your real payment also includes property taxes, homeowners insurance and, in a lot of 32092 neighborhoods, an HOA fee and a CDD assessment on the tax bill. None of that is optional, so budget for all of it before you fall in love with a house.
What is the VA 4% seller concession rule for World Golf Village buyers?
This is the part most VA buyers miss, and it’s the most useful tool you have at 7%.
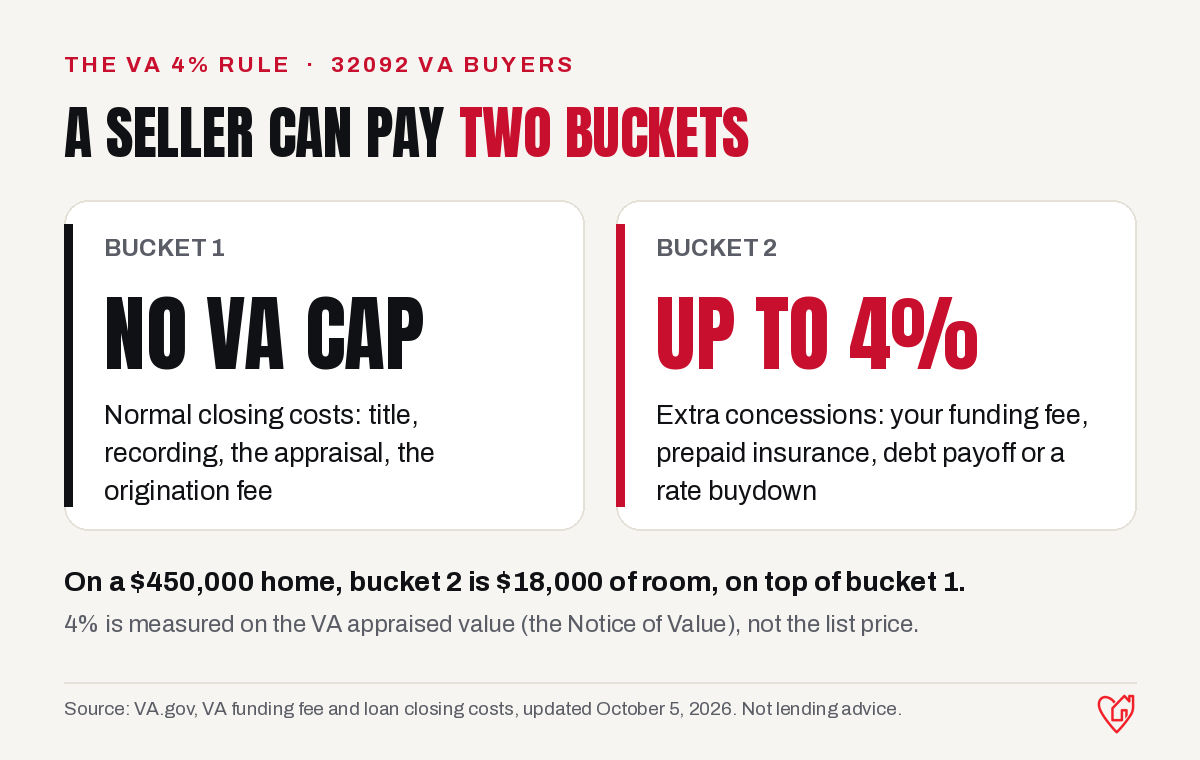
VA splits what a seller can pay into two buckets:
- Normal closing costs, with no VA cap. Things like title, recording, the appraisal and the loan origination fee. VA says it doesn’t limit seller credits for these.
- Concessions, capped at 4% of the home’s reasonable value. VA defines a concession as anything of value added to the deal at no cost to you, like paying your funding fee, paying off a debt, or prepaying your homeowners insurance.
That “reasonable value” comes from the VA appraisal, on a form called the Notice of Value. On a $450,000 home that appraises at price, 4% is $18,000 of room, on top of normal closing costs. Source: VA funding fee and closing costs page, updated October 5, 2026.
Picture two buckets on the closing table. Most buyers ask the seller to fill the first one and never touch the second.
Can a seller pay for a rate buydown on a VA loan?
Yes. A seller-paid temporary buydown is one of the most common uses of the 4% concession room, and lenders count it toward that 4% cap (Veterans United explains it here).
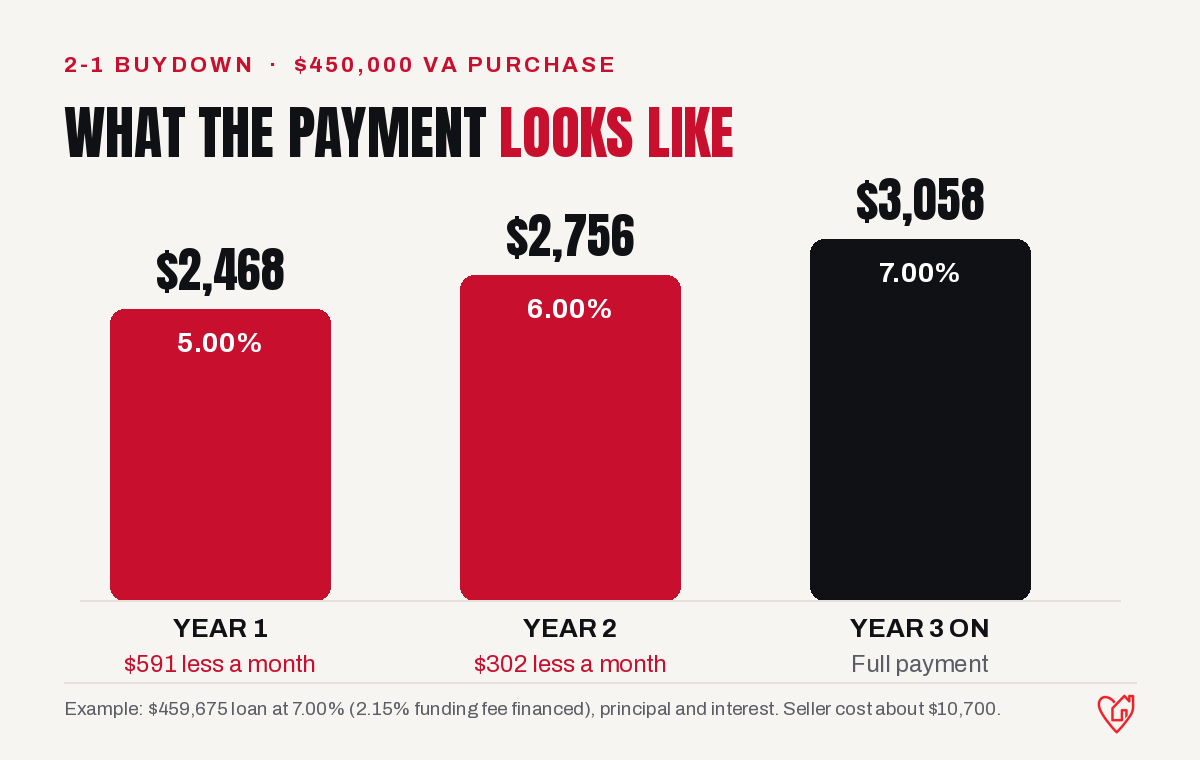
The most common version is a 2-1 buydown. The seller puts money in an account at closing, and it lowers your rate by 2 points in year one and 1 point in year two. Your actual note rate never changes.
On the same $459,675 loan at 7.00%:
- Year 1 at 5%: about $2,468 a month, roughly $591 less
- Year 2 at 6%: about $2,756 a month, roughly $302 less
- Year 3 on: the full $3,058
- Cost to the seller: about $10,700, around 2.4% of the price. That fits inside the $18,000 cap.
Two honest catches:
- You still qualify at the full rate. A temporary buydown lowers your first two years of payments. It doesn’t make you approved for a bigger loan.
- You can’t fit everything in 4%. On this example, a 2-1 buydown (about $10,700) plus having the seller pay your funding fee ($9,675) comes to about $20,400. That’s over the $18,000 cap. You’ll have to pick, and a lender can show you which one saves you more over the time you expect to own the home.
Rules, costs and lender overlays vary, so treat my math as a starting point and have a lender run your real numbers. My preferred lenders do VA loans regularly. If the terms are new to you, my Real Estate Dictionary covers seller concessions and closing costs in plain English.
Why World Golf Village and 32092 sellers are open to it right now
Look back at the table. In 32092, 43% of VA sales over the past year included seller concessions, with a median of about $13,400, and those buyers still paid a median 99.5% of the final list price. With rates over 7%, fewer buyers can afford the payment, and sellers know it.
A seller who’d rather not cut the price can often get to the same place with a concession, and the buyer gets a lower payment in the years it matters most. That’s a conversation worth having on almost every VA offer this fall.
How much is the VA funding fee?
For a VA purchase loan, the VA’s current chart (in effect since April 7, 2023, per VA.gov) is:
| Your down payment | First VA loan | After first use |
|---|---|---|
| Less than 5% | 2.15% of the loan | 3.3% of the loan |
| 5% to just under 10% | 1.5% | 1.5% |
| 10% or more | 1.25% | 1.25% |
You can roll the fee into the loan or pay it at closing. It’s the only closing cost VA lets you finance on a purchase.
Some veterans don’t pay it at all
You’re exempt if you receive VA compensation for a service-connected disability, are eligible for it but receive retirement or active-duty pay instead, are a surviving spouse receiving Dependency and Indemnity Compensation, have a qualifying pre-discharge rating before closing, or are on active duty and show proof of a Purple Heart by closing. Check your Certificate of Eligibility with your lender, because it can save you thousands.
What could trip up a VA purchase in 32092?
The VA appraisal and property standards
A VA appraiser checks the price and makes sure the home meets VA’s minimum property requirements. An appraisal is not an inspection, so VA strongly recommends getting a separate home inspection. If the value comes in low, you can ask for a reconsideration of value, renegotiate, or bring cash for the difference. Your contract should include the VA escape clause.
HOA and CDD documents
Most homes in 32092 sit in an HOA, and many newer communities also carry a CDD assessment on the property tax bill. I spent time as an HOA president in Samara Lakes, and the biggest lesson I took from it is that every community’s documents are different. Both count in your monthly budget and your lender’s math. Ask for the HOA documents and the latest tax bill early, and read them during your inspection period. If anything in them is unclear, ask the HOA or an attorney. I’m not able to interpret those documents for you, but I’ll make sure you have them in time to review.
Condos and townhomes
If you’re looking at a condo, ask your lender early whether the project works with a VA loan. It’s an easy question to answer up front and a painful one to discover three weeks into a contract.
Florida insurance
Get a homeowners insurance quote before you write an offer, especially on an older roof. In Florida, insurance can move your payment as much as the rate does.
What I would do if I were buying in World Golf Village with a VA loan this fall
- Get your Certificate of Eligibility now. You can request it online. Your lender can usually pull it too.
- Get preapproved with a lender who does VA loans every week. Ask them to show you a payment with no buydown, with a 2-1 buydown, and with the seller paying your funding fee.
- Budget the whole payment. Principal, interest, taxes, insurance, HOA and CDD. Not just the rate.
- Write the concession into your offer. Ask for normal closing costs plus a specific concession amount for the buydown or funding fee, inside the 4% cap.
- Keep a cushion under 4%. If the appraisal or prepaids shift, a deal right at the cap can go over late in the process.
- Get the inspection and read the HOA and CDD documents during your inspection period.
Frequently Asked Questions
Can I use a VA loan to buy a home in World Golf Village?
Yes. VA loans work anywhere the home meets VA’s minimum property requirements and appraises for the price. In 32092, 262 homes sold to VA buyers between October 2025 and September 2026, about 14% of all sales.
What is the VA 4% seller concession rule?
A seller can pay all of your normal closing costs with no VA cap, plus concessions up to 4% of the home’s reasonable value from the VA appraisal. Concessions include things like paying your funding fee, prepaying insurance or funding a rate buydown.
Can the seller pay for a rate buydown on a VA loan?
Yes. A seller-funded temporary buydown, like a 2-1, counts as a concession and has to fit inside the 4% cap. You still qualify at the full note rate.
What are VA loan rates in October 2026?
The average 30-year fixed VA rate was about 7.07% on October 7, 2026. Freddie Mac’s conventional 30-year average was 7.32% on October 22. Your rate depends on your credit, the lender and whether you pay points.
Is there a VA loan limit in St. Johns County?
Not if you have full entitlement. VA says buyers with full entitlement don’t have a loan limit, though the lender still has to approve the amount. If part of your entitlement is tied up in another VA loan, the county loan limit comes into play, so ask your lender.
Who is exempt from the VA funding fee?
Veterans receiving or eligible for VA compensation for a service-connected disability, some surviving spouses, service members with a qualifying pre-discharge rating, and active-duty Purple Heart recipients, per VA.gov.
Do I need a down payment for a VA loan in St. Augustine?
Usually not. Most VA buyers put nothing down, though putting 5% or more down lowers the funding fee.
Let’s look at your numbers, not the averages
Every number in this post is an example. Your payment depends on your entitlement, your funding fee status, the home and what the seller will do.
Send me a note through my contact page or start on my veteran homebuyer page. I’ll connect you with a lender who does VA loans every week, show you which 32092 neighborhoods fit your real payment, and help you write a concession into your offer the right way. You can read what past clients say on my testimonials page or learn more about me.
And if you’re on the other side of the table and wondering whether to accept a VA offer on your home, my Sell page is the place to start. Short answer: a well-prepared VA buyer is a strong buyer.
If the honest answer is “wait,” that’s what I’ll tell you. No pitch.
My family moved to Jacksonville from outside Chicago in 1990, and Northeast Florida has been home ever since. Today I live in St. Augustine, in 32092. I’m a Realtor® with iHeart Realty, Inc. and a Florida Army National Guard veteran: I enlisted in 1997 while I was still in high school, served 8.5 years, and was on active duty for a couple of years after 9/11. I buy investment property in this market myself, so I look at every deal with my own money in mind. This month I’m also taking the Military Relocation Professional course through NEFAR, because helping veterans and military families move is a big part of what I do.
This post is general information as of October 28, 2026, based on VA.gov, published VA rate data, Freddie Mac’s weekly survey and Northeast Florida MLS data. It is not lending, legal or tax advice. Rates change daily, and VA rules, lender requirements and your eligibility can change your numbers; talk to a licensed lender about your situation. VA eligibility and approval are not guaranteed.